Managing a credit card from a phone sounds simple until you need to check something at an inconvenient moment. I tested Aspire Account Center with that everyday problem in mind: not as a replacement for every financial tool, but as a focused mobile account center for people who want their Aspire credit card information close at hand. My overall impression is that it is most useful when a quick account check matters more than a broad budgeting dashboard.
This is a free finance app from Atlanticus Services, rated for Everyone and available for devices running Android 6.0 or later. Its current version is 4.22.47-6102, and the app has passed the half-million-install mark. The average rating sits at 3.3 from roughly 2,100 ratings, with about 967 written reviews, so the public response is mixed rather than universally enthusiastic. That matches my experience: the app can be practical, but its value depends heavily on your connection, your expectations, and how much control you want from a mobile card-management tool.
What the app is like when you need your account immediately
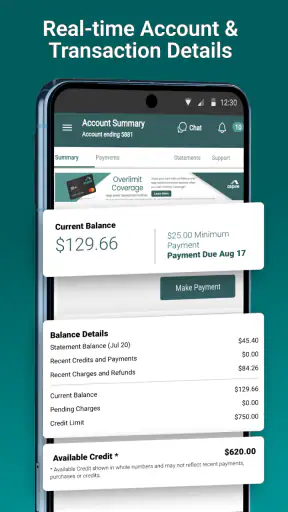
The strongest use case is a short, purposeful visit. I can imagine opening the app before making a purchase, checking whether a payment has appeared, or confirming the state of an Aspire account without sitting down at a computer. That narrow focus is a strength because it keeps the experience centered on the card relationship instead of mixing in investment tools, bank accounts, savings goals, or a complete household budget.
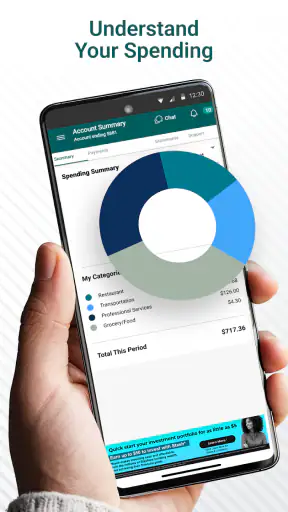
At the same time, that focus means this is not the right app for someone looking for a full personal-finance command center. If your main goal is to compare spending across several cards, categorize expenses from different banks, or plan a monthly budget in one place, a dedicated budgeting app or your primary banking app may be more suitable. Aspire Account Center makes more sense when the Aspire card itself is the account you need to monitor.
I also appreciate the difference between a card app and a general finance app. A general tool may collect information from multiple institutions, but it can introduce extra steps when all I want is to reach one specific account. Here, the narrower purpose can reduce that mental clutter. The trade-off is that I would not install it expecting a complete picture of my finances.
Why a network connection changes the experience
The important practical point is that account management depends on communication with the service. When I am connected reliably, the app feels like a convenient window into the account. When the connection is weak, delayed, or interrupted, the experience becomes less predictable because the information I need may not load at the moment I need it. I would therefore treat it as a connected account tool, not as something to rely on for disconnected access.
This matters in places where mobile service is inconsistent: underground transport, crowded venues, rural roads, or a building with poor indoor reception. A user who opens the app at the checkout counter may have a very different experience from someone who checks it at home on a stable connection. That is not a criticism unique to this app, but it is especially relevant for a financial tool, where uncertainty about whether a screen is current can be more stressful than a simple loading delay.
My practical habit would be to check the account before leaving home if I expect to need a detail during the day. That small change avoids turning a weak-signal moment into an urgent troubleshooting session. I would also avoid treating a screen that has not refreshed as proof that a payment, balance change, or transaction has not occurred. If the app cannot complete its connection, the safest conclusion is that I need to try again later or use another official access route.
Mobile situations where it earns its place
The app is at its most useful when the phone is already the device I have with me. Imagine receiving a purchase receipt while away from home and wanting to compare it with the card account. A focused app can be more convenient than opening a desktop browser, remembering a bookmarked page, and navigating through a larger website. The same applies when I want to check an account before making a purchase that might push my available credit closer to a limit.
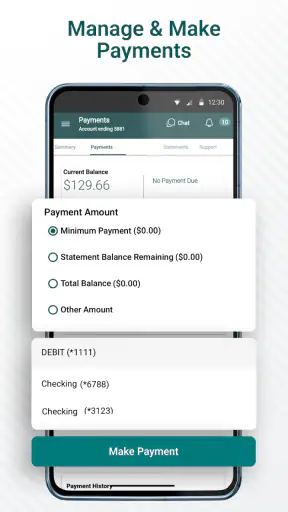
Another realistic situation is payment planning. If I am about to pay a bill from another account, I may want to look at the Aspire account first rather than rely on memory. The app gives that check a clear place in my routine. I would use it as part of a two-step habit: inspect the account, then make the payment or financial decision through the appropriate channel. That reduces the chance of acting on an old note or an incorrect assumption.
There is also a useful privacy advantage to keeping these checks on a personal phone rather than using a public computer. I still would not open a sensitive financial account on an unfamiliar device, and I would be careful around public Wi-Fi. The convenience of mobile access should not encourage careless access habits. A short account check is only helpful if I am also comfortable with the device and network I am using.
On a smaller phone, the experience may require more patience than it would on a desktop display. Financial information benefits from careful reading, and a compact screen can make it easier to overlook a label or misread a figure. I would slow down before confirming anything important, especially when moving between account details and a payment-related action. The app is designed for quick access, but quick should not mean rushed.
What to do when loading fails or information feels delayed
Connectivity problems are easier to handle when I separate them into two questions: is the app failing to connect, or am I looking at information that has not updated yet? Reopening the screen repeatedly does not solve either problem by itself. I would first check whether other apps can reach the internet, then switch between a reliable mobile connection and trusted Wi-Fi if available. After that, I would give the account screen a fresh attempt rather than assuming the first failed load represents the account’s actual state.
A useful recovery routine is to avoid making a financial decision while the account view is incomplete. If I am checking before a purchase, I can wait until the relevant information appears clearly. If I am checking after a payment, I can keep the confirmation from the payment method I used instead of interpreting a temporary display problem as a failed payment. This distinction is easy to miss when I am standing in a queue and want an immediate answer.
I would also keep the app updated through the normal app-store process. The installed version is 4.22.47-6102, and staying current is a sensible maintenance step for an account app because updates can affect compatibility and reliability. I would not, however, assume that updating guarantees instant access in a poor-signal location. Software freshness and network quality solve different problems.
If a problem continues, I would record what happened in plain terms: whether the app opened, whether the account screen loaded, and whether the issue appeared only on one connection. That information is more useful than simply saying that the app “did not work.” It also helps me decide whether the issue is temporary, device-specific, or serious enough to use another official account-access method.
Using it without wasting mobile data
For most people, an occasional account check should not be a major data event, but cautious habits still make sense. I would use a trusted Wi-Fi connection for longer sessions or updates and reserve mobile data for brief checks when I am away from home. I would also avoid repeatedly refreshing a screen that is clearly struggling to connect; repeated attempts add frustration without improving the underlying signal.
My more important data-saving tip is to plan the session before opening the app. Instead of launching it several times throughout a shopping trip, I would decide what I need to verify, perform one careful check, and close it. That is better for attention as well as data. Financial apps are easy to turn into compulsive refresh tools, especially when a recent transaction has not appeared yet.
Network caution also has a security side. I would prefer a private connection for account access and avoid entering sensitive information while connected to an unknown public network. A stable connection is convenient, but a familiar and trustworthy connection is more important. If I am unsure about the network, waiting until I can use a safer one is the sensible choice unless the situation is genuinely urgent.
People with limited data plans may also prefer checking at home before going out. That approach is particularly practical if the account information is needed for planning rather than for an immediate transaction. The app works best when it becomes part of a deliberate routine, not when it is repeatedly opened in the hope that a weak connection will suddenly improve.
Where it differs from the usual alternatives
The most obvious alternative is using a browser. A browser can be better when I am already on a computer, need to compare several pages, or prefer a larger screen for financial details. Aspire Account Center is better suited to the quick mobile visit: open the dedicated tool, check the account, and leave. Neither approach is automatically superior; the right choice depends on whether speed or screen space matters more at that moment.
A second alternative is a general banking or budgeting app. Those tools may be more useful for a complete financial overview, especially if I manage several institutions. They can show broader spending patterns, but they may also require account connections, synchronization, or navigation through features unrelated to the Aspire card. I would choose the broader tool for planning and this app for a direct account check.
There is a trade-off in keeping both options. A dedicated card app can reduce the number of steps for one account, while a broader app can reduce the number of apps I need to consult overall. If I only use an Aspire card occasionally, the browser may be enough. If I check it regularly from my phone, a dedicated app is easier to justify. The decision should be based on habit, not on the assumption that every financial task belongs in one application.
Who should use it, and who should look elsewhere
I would recommend Aspire Account Center to an Aspire cardholder who wants a straightforward mobile place to monitor the account and is comfortable working with a connected service. It is also a reasonable fit for someone who prefers checking a card directly instead of combining it with a wider budgeting system. The free price removes a common barrier to trying it, although the real benefit comes from whether the app fits your routine.
I would be more cautious if your phone is old, your connection is frequently unreliable, or you need a detailed financial dashboard. The minimum operating-system requirement is Android 6.0, which makes the app accessible to older Android devices, but compatibility alone does not guarantee a smooth experience on every handset. If your main financial work happens on a laptop, the browser may remain more comfortable.
I would also skip it as a primary tool if you need one place to manage accounts from multiple providers. A dedicated Aspire account center is not a substitute for a complete financial-planning system. In that situation, use a broader tool for the overview and keep this app only if its direct access saves you time.
My connectivity verdict
After looking at the app through the lens of real mobile use, I see Aspire Account Center as a focused companion rather than an all-purpose finance solution. Its best moments are brief and practical: checking an Aspire card while away from a computer, confirming account information before making a decision, and keeping one account within easy reach. Its weakest moments are tied to uncertainty around connection and refresh timing, which means I would not depend on it blindly in a poor-signal situation.
The mixed average rating of 3.3 reflects why expectations matter. This is not an app I would choose for sophisticated budgeting, multi-bank analysis, or offline financial planning. I would choose it when direct mobile access to an Aspire credit card is the priority. My advice is to use it as a convenient connected checkpoint, while keeping a calm backup plan for moments when the network or the app does not respond.
For the right user, that is enough to make it worthwhile. I would install it if I held an Aspire card and regularly needed account information while out. I would not install it simply because it belongs to the finance category. Its usefulness is specific, and that specificity is both its main advantage and its clearest limitation.


